UAE Corporate Tax – Qualifying Activity, Case Studies, VAT Connection & Documentation
On This Page
1. Overview
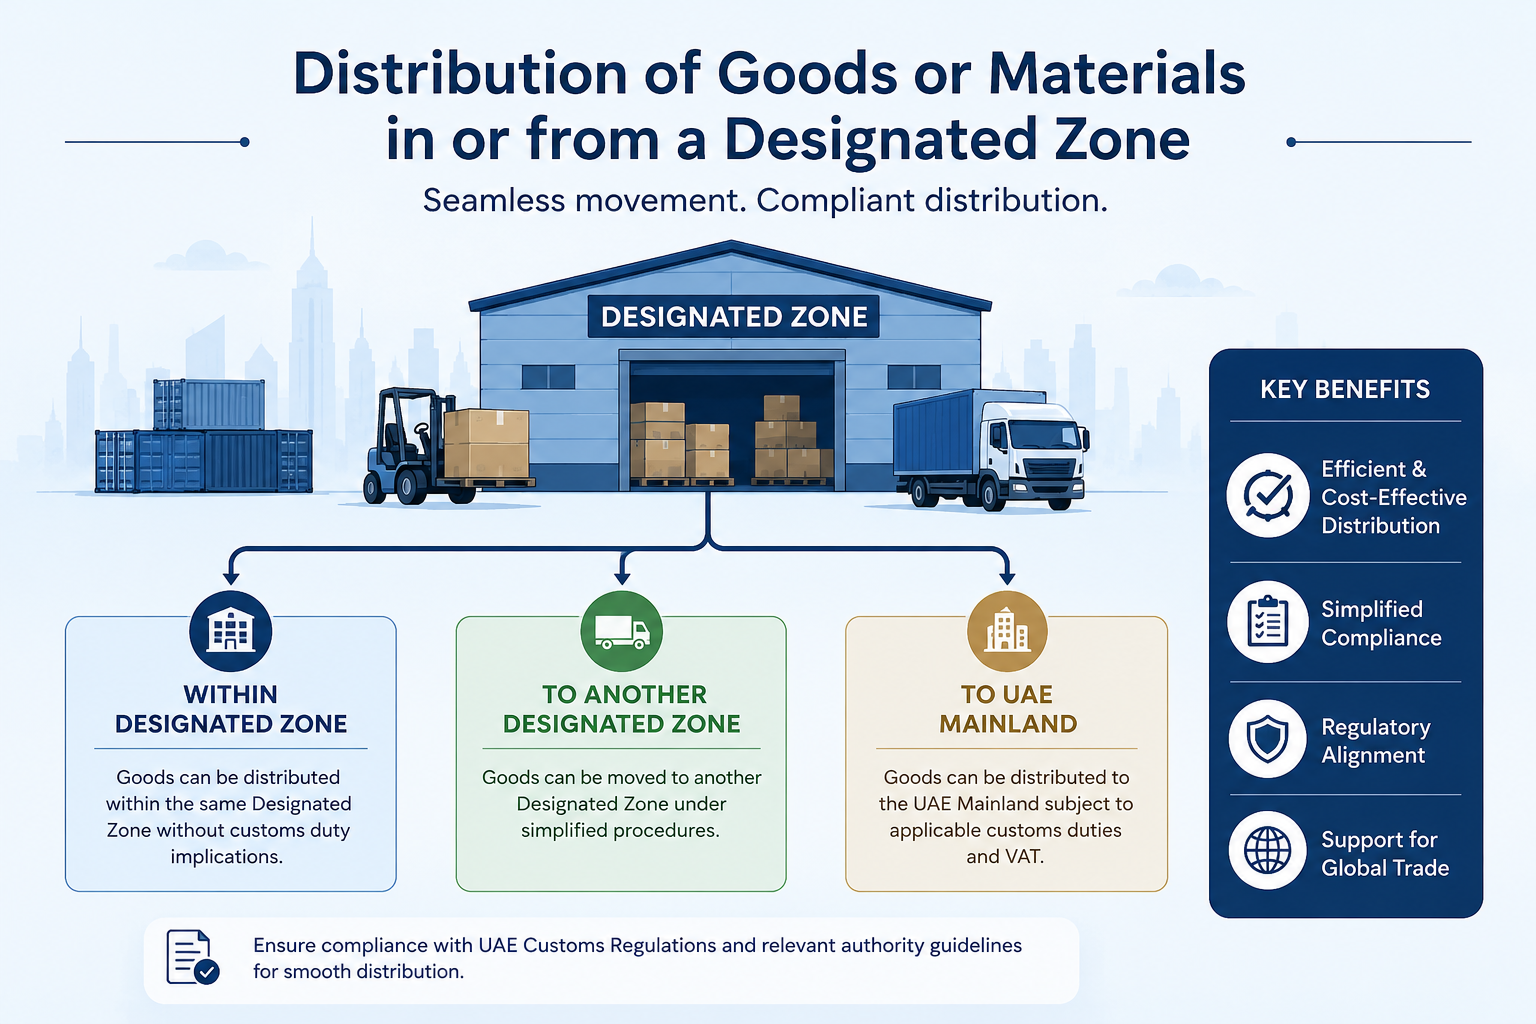
Distribution in a Designated Zone refers to the purchase, holding and resale of tangible, movable goods or materials, where the distributor holds legal title to the goods and performs activities such as importation, storage, inventory management, transportation and resale.
When specific conditions are met, this activity can qualify for the 0% Free Zone Corporate Tax regime under the UAE Corporate Tax framework.
2. Qualifying Conditions for Distribution
- Location: Activities are conducted in or from a Designated Zone.
- Goods: Goods are tangible and movable (no standalone intangibles such as licences or software).
- Customer: Customer is a reseller or processor, not an end user.
- Import route: Foreign goods entering the UAE are imported through the Designated Zone when sold to UAE customers.
- Title: The distributor holds legal title to the goods.
Note
Manufacturer → Distributor (Designated Zone) → Reseller / Processor → End User ✔ Qualifying Distribution
Manufacturer → Distributor (Designated Zone) → End User ✘ Non-Qualifying Distribution
3. Included and Ancillary Activities
3.1 Core Distribution Activities
- Purchase and resale: Buying goods from manufacturers or suppliers and reselling to retailers or distributors.
- Warehousing: Storage of goods in secure facilities within or from the Designated Zone.
- Transportation & delivery: Movement of goods from warehouse or supplier to reseller or customer.
- Inventory management: Monitoring stock levels, orders, sales and deliveries.
- Order processing: Receiving and processing orders and arranging delivery.
- Packaging & repackaging: Branding, instructions, warranty information and improved packaging.
3.2 Ancillary Activities
Ancillary activities may be treated as part of the Qualifying Activity when they naturally and integrally complement the main distribution activity:
- Marketing & advertising: Promotion of products to drive sales volume.
- Quality control & inspection: Ensuring goods meet required standards before delivery.
- Customer support: Handling queries, complaints and feedback related to distributed goods.
Ancillary activities do not become Qualifying Activities on a standalone basis. They must be linked to a core distribution activity that itself meets the Qualifying Activity conditions.
4. Case Studies
4.1 Case Study 1 – High-Sea Sales / Third Port Trading (Qualifying)
Scenario: Company C, a Free Zone Person in a Designated Zone, buys goods from a manufacturer in Country A and sells them to a distributor in Country B. Goods are shipped directly from Country A to Country B and never enter the UAE.
Analysis:
- Activities are performed from a Designated Zone.
- Goods do not enter the UAE, so import-through-DZ condition is not relevant.
- Customer is a distributor (reseller), not an end user.
Conclusion: Company C is performing a Qualifying Distribution Activity.
4.2 Case Study 2 – Import into UAE Through Designated Zone (Qualifying)
Scenario: Company D, a Free Zone Person in a Designated Zone, buys goods from Country A and sells them to a retailer in the UAE. Goods are shipped to Company D in the Designated Zone and then imported into the UAE.
Analysis:
- Goods enter the UAE through the Designated Zone.
- Customer is a retailer (reseller), not an end user.
- Activities are conducted in or from the Designated Zone.
Conclusion: Company D is performing Qualifying Activities. If goods were imported through a non-DZ port, the activity would not qualify.
4.3 Case Study 3 – Export of Goods Already in UAE (Qualifying)
Scenario: Company E, a Free Zone Person in a Designated Zone, buys goods from a UAE mainland manufacturer and sells them to a distributor outside the UAE. Goods are shipped directly from the manufacturer to the foreign distributor.
Analysis:
- Goods were already in the UAE when purchased by Company E.
- No requirement for goods to pass through the Designated Zone again.
- Customer is a foreign distributor (reseller).
Conclusion: Company E is performing Qualifying Distribution Activities.
4.4 Case Study 4 – Distribution Within UAE (Qualifying)
Scenario: Company F, a Free Zone Person in a Designated Zone, buys goods from a UAE mainland supplier and sells them to a UAE mainland retailer. Goods move directly from supplier to retailer.
Analysis:
- Goods are already in the UAE at the time of purchase.
- Customer is a retailer (reseller), not an end user.
- Activities are conducted in or from the Designated Zone.
Conclusion: Company F is performing Qualifying Distribution Activities.
4.5 Case Study 5 – Sale to End User (Non-Qualifying)
Scenario: A Free Zone Person in a Designated Zone sells laptops directly to individuals for personal use, or sells office furniture to a company for its own consumption.
Analysis:
- Customers are end users who consume the goods.
- No further resale or processing for resale.
Conclusion: This activity is not a Qualifying Distribution Activity.
5. VAT Connection
Designated Zones have a special treatment under UAE VAT for goods, subject to strict conditions. However, for Corporate Tax, the focus is on the nature of the activity, the location of performance, and the type of customer.
- VAT: Certain movements of goods in Designated Zones may be treated as outside the UAE VAT territory.
- Corporate Tax: Distribution in or from a Designated Zone can qualify for 0% tax if the conditions for Qualifying Activities are met.
- Link: VAT documentation (customs records, movement of goods, inventory control) supports Corporate Tax qualification by evidencing the flow and control of goods.
6. Common Mistakes
- Selling to end users: Treating end-user sales as qualifying distribution.
- Incorrect import route: Importing foreign goods through mainland ports instead of the Designated Zone.
- Assuming all Free Zone trading qualifies: Only Designated Zone distribution that meets conditions qualifies.
- Confusing logistics with distribution: Logistics services without ownership of goods do not qualify.
- Weak documentation: Lack of KYC, customer undertakings, and movement records.
7. Documentation Requirements
Robust documentation is essential to substantiate the Qualifying Activity status and the 0% Corporate Tax position.
- Customer KYC: Know Your Client procedures and records.
- Resale undertakings: Written confirmations that customers are resellers or processors.
- Contracts: Agreements specifying resale or processing for resale.
- Import/export documents: Customs declarations, bills of lading, airway bills.
- Inventory records: Stock movement logs, ERP reports, reconciliation statements.
- Delivery documentation: Delivery notes, shipping instructions, proof of movement.
- Designated Zone evidence: Proof that activities are conducted in or from the Designated Zone.
8. Summary Chart – Qualifying vs Non-Qualifying
| Scenario | Goods Enter UAE? | Must Enter Through DZ? | Customer Type | Qualifying? |
|---|---|---|---|---|
| High-sea sales / third port trading | No | No | Reseller | Yes |
| Import into UAE via Designated Zone | Yes | Yes | Reseller | Yes |
| Export of goods already in UAE | Yes (already in UAE) | No | Foreign reseller | Yes |
| Distribution within UAE (goods already in UAE) | Yes (already in UAE) | No | UAE reseller | Yes |
| Sale to end user | Irrelevant | Irrelevant | End user | No |
9. Frequently Asked Questions (FAQ)
Q1. Does selling to a UAE retailer qualify as distribution?
A1. Yes, provided the retailer is not an end user and, for foreign goods, the goods enter the UAE through the Designated Zone.
Q2. Do goods already in the UAE need to pass through the Designated Zone?
A2. No. If goods are already in the UAE when purchased, they do not need to re-enter the Designated Zone to qualify.
Q3. Does logistics alone qualify as a distribution activity?
A3. No. Logistics services without ownership of goods are not qualifying distribution activities.
Q4. Are intangible products such as licences or software included?
A4. No. Only tangible, movable goods qualify. Embedded software that cannot be separately identified from the goods is not excluded.
Q5. What is the impact of selling to end users?
A5. Sales to end users are not qualifying distribution activities and may be subject to the standard 9% Corporate Tax rate.
10. How Holistic Solutions Can Help
Holistic Solutions and Trade FZ LLC supports Free Zone businesses in navigating the complex requirements of UAE Corporate Tax, particularly for Qualifying Activities such as Distribution of Goods or Materials in or from a Designated Zone. Our expertise ensures that your operations, documentation, and compliance framework fully align with regulatory expectations—protecting your eligibility for the 0% Free Zone Corporate Tax regime.
Book a consultation and we will assess which structure fits your situation in 30 minutes.